
Cisco is a secure-networking company serving enterprises, governments, telecom operators and hyperscale cloud providers. Switching and routing remain central to revenue, while security, observability and recurring software have become more important following the Splunk acquisition. That mix gives Cisco direct exposure to AI infrastructure and campus upgrades, though it also leaves the stock sensitive to hardware margins, customer spending cycles and acquisition execution.
The latest quarter showed a powerful networking cycle with a less favorable product mix. Cisco Q4 FY2026 revenue reached $17.3 billion, up 18% year over year, and non-GAAP EPS rose 23% to $1.22. Product orders grew 35% and annual AI infrastructure orders reached $9.3 billion, though non-GAAP gross margin declined to 66.3% as hardware expanded faster than services.
The CSCO stock forecast for 2026 now centers on two competing views:
- The AI networking and campus-refresh case: Hyperscaler AI revenue, campus refreshes and Splunk-led security demand could keep revenue and EPS expanding above historical rates.
- The margin and valuation case: A hardware-heavy mix, slowing order comparisons and rich valuation could prevent revenue growth from producing enough per-share upside.
This guide breaks down the CSCO stock forecast, 2026 price scenarios, key risks and analyst outlooks, drawing on Cisco's August 12, 2026 Q4 FY2026 earnings release, quarterly filing and market data through September 11, plus how to trade CSCO stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Cisco Investors to Know in September 2026
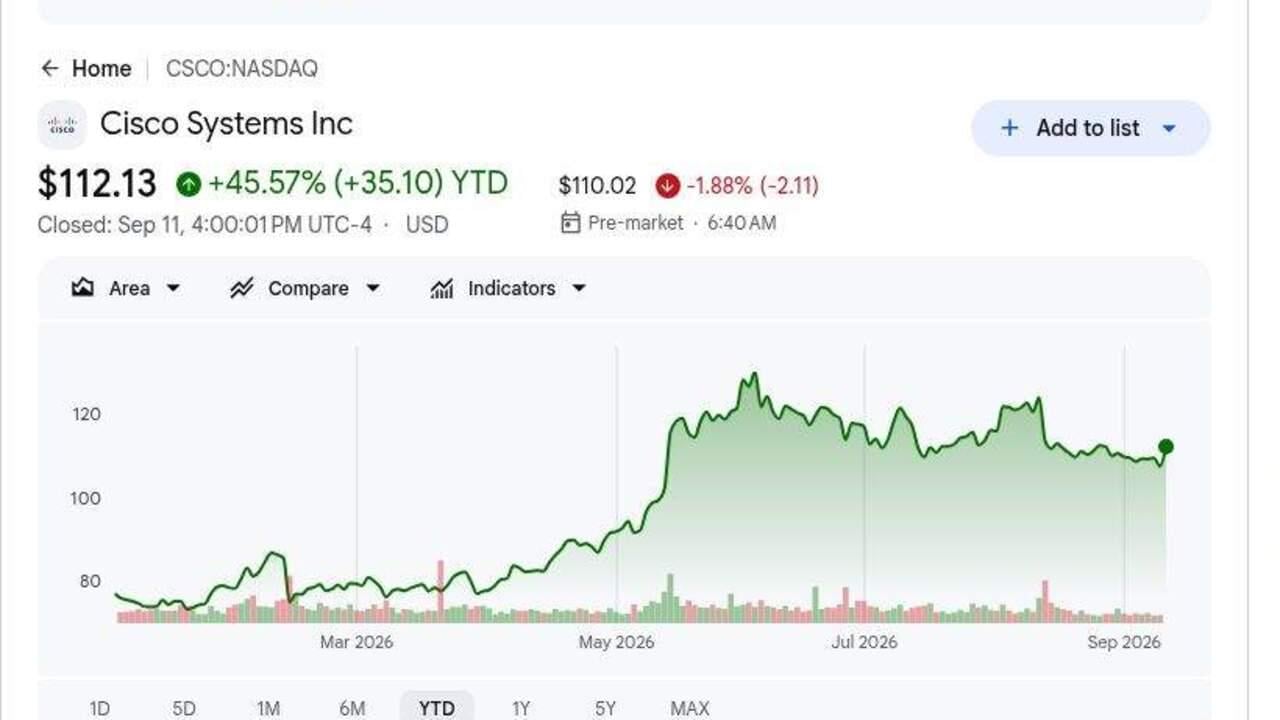
- CSCO closed at USD 112.13 on September 11 after gaining about 45% YTD: The rally reflects stronger AI networking demand and an enterprise upgrade cycle. The USD 139.62 average analyst target still implies upside, though the USD 122 to USD 170 range shows wide disagreement.
- Q4 revenue reached USD 17.3 billion, up 18%: Revenue beat the USD 16.9 billion guidance ceiling by USD 352 million, while non-GAAP EPS of USD 1.22 topped the USD 1.18 ceiling. Broad product demand supported the beat.
- Product orders rose 35% and networking orders increased 40%: Orders still grew 25% excluding hyperscalers, while networking posted an eighth straight quarter of double-digit growth. The refresh cycle therefore extends beyond AI cloud customers.
- FY2026 AI infrastructure orders reached USD 9.3 billion: Cisco booked USD 4 billion in Q4 alone and generated about USD 4 billion of related annual revenue. Management expects that contribution to rise to USD 7.5 billion in FY2027.
- FY2027 revenue guidance reached USD 72.2 billion to USD 73.4 billion: The USD 72.8 billion midpoint implies about 15% growth from FY2026. The main tradeoff is Q4 non-GAAP gross margin, which fell 2.1 percentage points year over year to 66.3%.
What Is Cisco (CSCO)?
Cisco supplies the networking hardware, security software, observability tools and collaboration products that enterprises, governments, service providers and cloud operators use to connect and protect digital infrastructure. Its portfolio spans campus switches and wireless systems, data-center networking, routing, firewalls, Webex and technical services. The $28 billion Splunk acquisition expanded security analytics and observability, adding more recurring software revenue to a business still driven by large product cycles. Q4 product revenue grew 24%, while services revenue was flat, showing that hardware demand currently carries more of the growth burden.
Cisco's long-term strategy centers on secure AI infrastructure across hyperscale data centers and enterprise networks. Silicon One systems, high-speed Ethernet, optics and Nexus switching support AI clusters, while Splunk, ThousandEyes and security products provide telemetry and protection across hybrid environments. Cisco works closely with NVIDIA on integrated AI infrastructure and expects AI revenue from hyperscalers to rise from about $4 billion in FY2026 to $7.5 billion in FY2027. A multi-year campus refresh is developing alongside this hyperscaler cycle, broadening demand beyond a small set of cloud customers.
Read More: Top AI Networking Stocks 2026: AI Fabric, Switches, Copper, Fiber and Optical Connectivity
Cisco (CSCO) Q4 FY2026 Earnings Overview: Revenue, EPS and Growth Drivers
Cisco delivered record Q4 revenue of $17.3 billion versus a $16.9 billion guidance ceiling, non-GAAP EPS of $1.22 versus a $1.18 ceiling, product-order growth of 35% and operating cash flow of $5.4 billion. FY2026 AI infrastructure orders reached $9.3 billion, and management expects $7.5 billion of related revenue in FY2027, though a heavier hardware mix reduced non-GAAP gross margin to 66.3%.
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q4 FY2026 revenue |
$16.7B–$16.9B guidance |
$17.3B |
Beat. $352M above the guidance ceiling and up 18% YoY. |
|
Q4 non-GAAP diluted EPS |
$1.16–$1.18 guidance |
$1.22 |
Beat. $0.04 above the guidance ceiling and up 23% YoY. |
|
Q4 GAAP net income |
$2.55B one year earlier |
$3.86B |
Improved. Increased 51% YoY. |
|
Q4 product orders |
— |
+35% YoY |
Accelerated. Growth was 25% excluding hyperscalers. |
|
Q4 networking product orders |
— |
+40% YoY |
Expanded. Marked an eighth consecutive double-digit-growth quarter. |
|
FY2026 AI infrastructure orders |
Prior expectation above $5B |
$9.3B |
Exceeded. Included $4B booked in Q4. |
|
Q4 operating cash flow |
$4.2B one year earlier |
$5.4B |
Improved. Increased 27% YoY. |
|
Q1 FY2027 revenue outlook |
— |
$18.0B–$18.2B |
Guided. Midpoint implies about 5% sequential growth. |
|
FY2027 revenue outlook |
— |
$72.2B–$73.4B |
Guided. Midpoint implies roughly 15% growth. |
|
FY2027 AI infrastructure revenue |
FY2026 actual about $4B |
$7.5B expected |
Raised. Implies an 87.5% annual increase. |
- Revenue of USD 17.3 billion exceeded guidance by at least USD 352 million: Sales rose 18%, led by 24% product growth, while services revenue was flat. The mix shows that current momentum is concentrated in hardware and networking demand.
- Non-GAAP EPS of USD 1.22 topped guidance by USD 0.04: Non-GAAP operating income increased 23% to USD 6.2 billion. Higher volume is still translating into operating leverage.
- Networking product orders grew 40% for an eighth straight double-digit quarter: Total product orders rose 35%, while orders excluding hyperscalers increased 25%. That points to broad enterprise demand beyond AI cloud customers.
- Q4 operating cash flow increased 27% to USD 5.4 billion: Cisco returned USD 3.2 billion through buybacks and dividends while retaining USD 15.9 billion of cash and investments. Strong cash generation supports both shareholder returns and continued investment.
- FY2027 AI infrastructure revenue is expected to reach USD 7.5 billion: That compares with about USD 4 billion in FY2026 and supports revenue guidance of USD 72.2 billion to USD 73.4 billion. Faster hardware growth could still pressure margins.
Read More: Top AI Networking Stocks 2026: AI Fabric, Switches, Copper, Fiber and Optical Connectivity
Cisco (CSCO) 2026 Investment Outlook: $170 Bull Case vs. $90 Bear Case
The 2026 outlook depends on whether AI networking growth, enterprise upgrades and software expansion can support Cisco's current valuation. The following ranges are BingX Academy editorial scenarios rather than Wall Street forecasts.
The Bull Case: Strong AI Networking Demand Pushes CSCO Toward USD 170
The Bull Case assumes AI infrastructure revenue reaches or exceeds the USD 7.5 billion FY2027 expectation, while enterprise upgrades keep networking orders strong. Splunk also expands recurring security and observability revenue, reducing reliance on hardware cycles.
A move toward USD 170 would require revenue near the upper end of USD 72.2 billion to USD 73.4 billion, better software mix and stable gross margin. Continued order growth excluding hyperscalers would strengthen the case.
The Base Case: Steady Networking Demand Keeps CSCO Between USD 120 and USD 145
The Base Case assumes AI and campus orders convert into revenue as planned, though faster product growth keeps gross margin below prior peaks. Splunk adds recurring revenue, but hardware remains the main growth driver.
Under this scenario, CSCO could trade mainly between USD 120 and USD 145. FY2027 revenue within guidance, AI revenue near USD 7.5 billion and product-order growth above 15% would support the range. Gross margin below 65% would weaken the upper end.
The Bear Case: Slower Orders and Margin Pressure Pull CSCO Toward USD 90
The Bear Case assumes hyperscaler orders cool after a strong investment cycle, enterprise upgrades slow and hardware remains a larger share of revenue. Component costs and pricing pressure then weaken gross margin before software growth can offset the slowdown.
A move toward USD 90 would become more likely if product orders turn negative, AI revenue falls short of USD 7.5 billion or non-GAAP gross margin drops below 65%. Slower EPS growth and a lower valuation multiple would add further pressure.
CSCO Stock Price Forecasts for 2026 By Wall Street Analysts
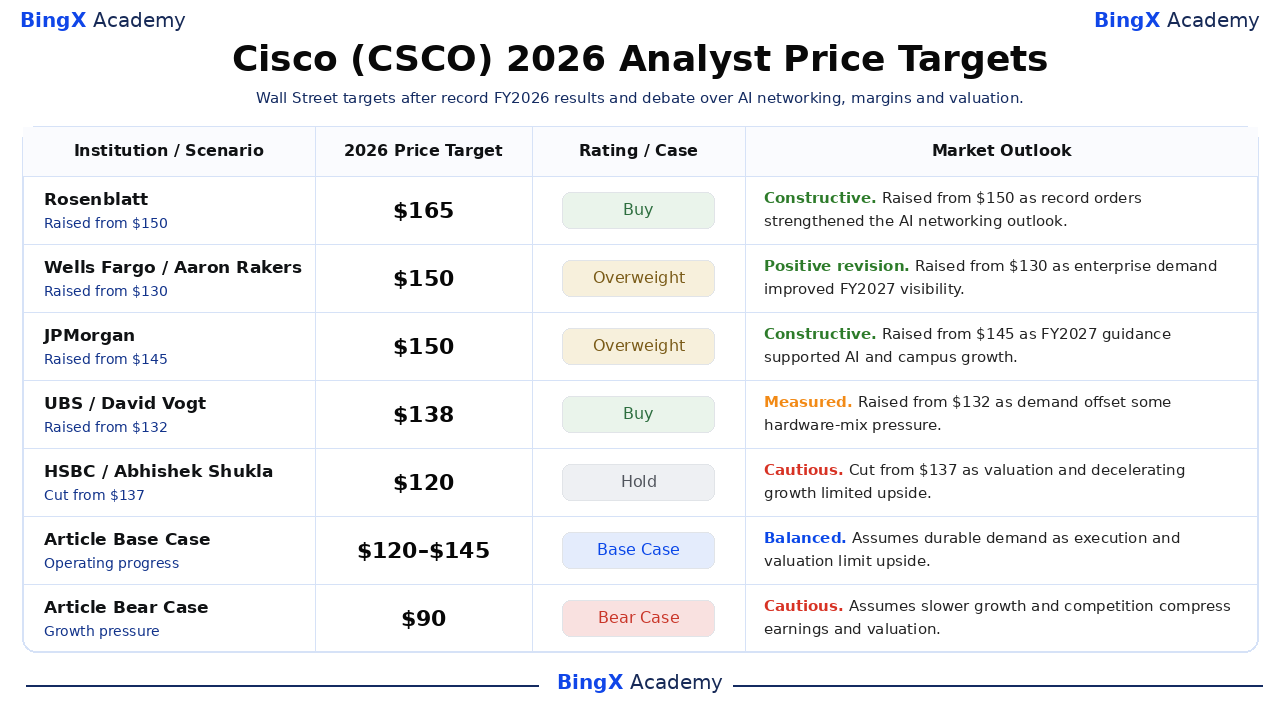
These five dated actions are sorted from highest to lowest and show how analysts weigh growth, competition, margin and valuation. They are third-party reference points rather than price promises. The final Base and Bear rows are BingX Academy editorial scenarios.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Rosenblatt / Mike Genovese |
$165 |
Buy |
Constructive. August 13: raised from $150 as record orders and AI infrastructure momentum strengthened Cisco's multi-year networking growth outlook. |
|
Wells Fargo / Aaron Rakers |
$150 |
Overweight |
Positive revision. August 13: raised from $130 as broad enterprise demand and stronger fiscal 2027 revenue visibility supported a higher target. |
|
JPMorgan / Samik Chatterjee |
$150 |
Overweight |
Constructive. August 14: raised from $145 as the firm saw the fiscal 2027 outlook as support for continued AI and campus networking growth. |
|
UBS / David Vogt |
$138 |
Buy |
Measured. August 13: raised from $132 as strong enterprise and hyperscaler demand supported estimates, though product mix could pressure gross margin. |
|
HSBC / Abhishek Shukla |
$120 |
Hold |
Cautious. August 14: cut from $137 as the downgrade reflected valuation and decelerating-growth concerns despite strong Q4 execution. |
|
Article Base Case |
$120–$145 |
Base Case |
Balanced. Assumes durable demand as execution and valuation limit upside. |
|
Article Bear Case |
$90 |
Bear Case |
Cautious. Assumes slower growth and competition compress earnings and valuation. |
How to Trade Cisco (CSCO) Stock on BingX
Trade Cisco's AI-networking, campus-refresh and margin outlook using BingX TradFi and BingX AI tools. Because CSCO can react sharply to earnings, guidance and product updates, traders should define both the catalyst and risk limits before entering a position.
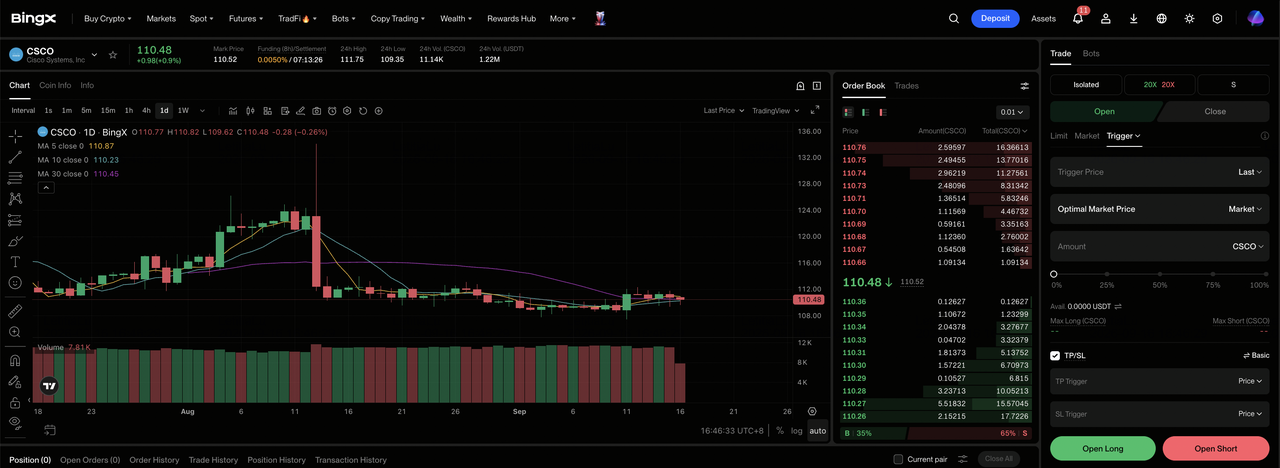
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Cisco (CSCO). Search for and select the CSCO-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if growth and margins support the Bull Case. Select Open Short if competition or execution weakens expected per-share economics.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The stock's 2026 volatility shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. CSCO can react quickly to results, guidance, analyst revisions and industry news.
Top 5 Risks to Watch for Cisco Investors in 2026
Cisco's outlook depends on product mix, customer demand, integration and valuation. These risks can affect earnings, cash flow and the multiple assigned to the stock.
- Hardware growth could pressure margins: Product revenue rose 24% while services were flat, and non-GAAP gross margin fell 2.1 points to 66.3%. A heavier hardware mix could limit EPS upside even if revenue stays strong.
- Hyperscaler orders could remain volatile: Cisco booked USD 4 billion of AI orders in Q4. Delays from a small group of cloud customers could create sharp swings in quarterly order growth.
- Enterprise upgrades could slow after the current cycle: Networking orders rose 40% for an eighth straight double-digit quarter. Longer replacement cycles could weaken revenue growth and inventory efficiency.
- Splunk integration still needs to deliver returns: Cisco paid USD 28 billion for Splunk. Weak cross-selling or higher integration costs could reduce the expected return from the acquisition.
- The higher valuation leaves less room for misses: CSCO gained about 45% YTD and traded near USD 112.13. Revenue below the USD 72.2 billion FY2027 floor or gross margin below 65% could pressure the valuation multiple.
Final Thoughts: Should You Invest in Cisco in 2026?
Cisco entered FY2027 with record $17.3 billion quarterly revenue, $9.3 billion of annual AI orders and 40% networking-order growth. Those figures support the supercycle thesis, though a hardware-heavy mix and high comparisons raise the execution threshold. Gross-margin stability and broad enterprise orders should show whether the expansion can remain profitable over time.
The Bull Case supports $170 if growth translates into stronger per-share earnings. The Bear Case points to $90 if competition, margin or execution pressure weakens estimates. Conservative traders may wait for the next revenue, recurring-growth and margin updates before increasing exposure. That evidence offers a clearer basis for choosing between the two scenarios and controlling position size.
Risk Reminder: Trading and investing in equities like CSCO involves a high risk of capital loss. Earnings misses, guidance changes, competition, valuation shifts and leveraged trading can produce rapid losses. Conduct independent research before allocating capital.
Related Reading
- Top AI Networking Stocks 2026: AI Fabric, Switches, Copper, Fiber and Optical Connectivity
- Top AI Optical Stocks to Buy in 2026: Photonics, Optics, Fiber, and Data Center Interconnects
- Nvidia (NVDA) Stock Price Outlook for 2026: Can Blackwell and Vera Rubin Take NVDA Back to $300?
- Broadcom (AVGO) Price Prediction 2026: Can AI Revenue Growth Push AVGO Toward $600?
- Marvell (MRVL) 2026 Outlook: Can AI & Silicon Momentum Drive Stock to $150?
- Credo Technology (CRDO) Price Prediction 2026: $300 AEC Hyper-Ramp or Premium Valuation Speedbump?
