Alibaba Group (BABA) operates digital commerce, cloud computing, logistics and consumer-service platforms across China and international markets. Taobao and Tmall remain central to the group, while Alibaba Cloud, Qwen artificial intelligence, instant retail and international commerce are becoming more important to long-term growth. This transition expands Alibaba's exposure to AI demand, yet it also leaves the ADR sensitive to capital intensity, commerce competition and China-related policy risk.
The latest quarter showed that transition is advancing faster on revenue than on earnings. Alibaba Q1 FY2027 revenue increased 9% to RMB 268.953 billion (USD $39.63 billion), AI Cloud and Compute revenue rose 45% to RMB 48.437 billion (USD $7.14 billion) and cloud adjusted EBITA grew 133%. Adjusted EPS per ADS of RMB 8.52 (USD $1.26 per ADS) missed the RMB 10.72 (USD $1.58 per ADS) consensus as AI infrastructure and commerce investment reduced near-term profitability.
The BABA stock forecast for 2026 now centers on two competing views:
- The AI monetization case: 45% cloud growth, expanding cloud margins and Qwen adoption convert Alibaba's infrastructure investment into a larger, more profitable recurring revenue base.
- The return-pressure case: heavy capital expenditure, instant-retail competition, equity dilution and weak domestic consumption keep cash flow and earnings below the level needed for a durable re-rating.
This guide breaks down the BABA ADR forecast, 2026 USD price scenarios, key risks and analyst outlooks, drawing on Alibaba's August 20 Q1 FY2027 earnings release, official filing and market data through September 4, plus how to trade BABA stock futures on BingX TradFi with USDT collateral.
Top 5 Things for Alibaba Investors to Know in September 2026
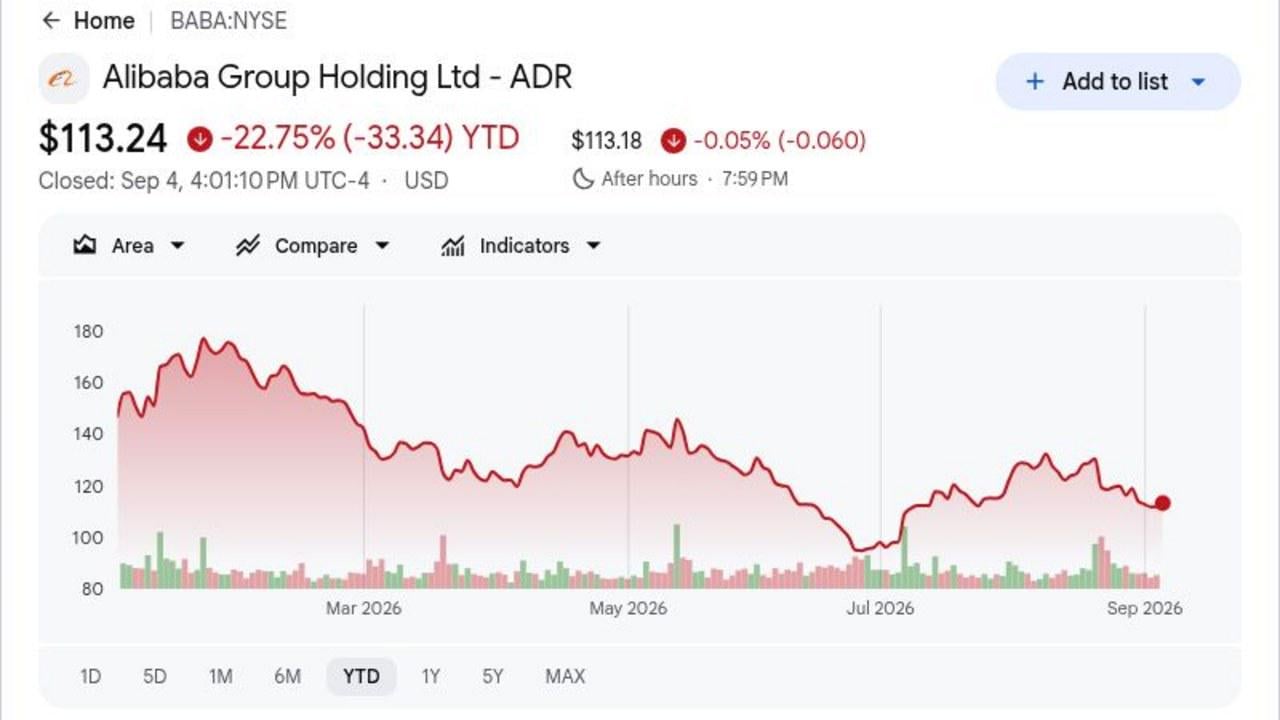
- BABA was down 22.75% YTD through September 4: Shares closed at $113.24, well below the $192.67 52-week high. The decline shows that investors still want clearer proof that heavy AI spending can translate into stronger earnings and cash flow.
- Quarterly revenue reached RMB 268.953 billion ($39.63 billion), up 9% year over year: Revenue beat the roughly RMB 262.1 billion ($38.62 billion) consensus by about RMB 6.9 billion ($1.02 billion), but adjusted EPS of RMB 8.52 ($1.26 per ADS) missed the RMB 10.72 ($1.58) estimate.
- AI Cloud and Compute revenue grew 45% to RMB 48.437 billion ($7.14 billion): This marked Alibaba’s fastest cloud growth in 22 quarters. AI-related product revenue reached RMB 12.376 billion ($1.82 billion) and posted triple-digit growth for a twelfth straight quarter.
- Quarterly capex rose 75% to RMB 67.7 billion ($9.98 billion): The spending supported AI compute expansion, while cloud adjusted EBITA still rose 133% to RMB 5.628 billion ($0.83 billion). Alibaba ended the quarter with about $69.9 billion in cash and liquid investments.
- Alibaba raised HK$80 billion for full-stack AI investment: The company issued 710 million new shares at HK$112.70, with proceeds earmarked for chips, infrastructure, and model development. The funding strengthens the AI buildout, but the roughly 3.7% increase in shares outstanding creates a clear dilution tradeoff.
What Is Alibaba Group (BABA)?
Alibaba Group is a Chinese technology company whose revenue engines span commerce, cloud computing, logistics and digital services. Taobao and Tmall connect consumers, merchants and brands in China, Alibaba.com serves global wholesale trade, and AliExpress, Lazada and Trendyol extend the group internationally. Cainiao provides logistics capabilities, while Alibaba Cloud sells infrastructure, databases, security and AI services. The New York-listed BABA security is an American depositary receipt representing exposure to Alibaba's ordinary shares.
Alibaba's current strategy concentrates investment around full-stack AI and consumption. The Qwen model family has surpassed 3 billion downloads and 300,000 derivative models, creating an open-source funnel for Alibaba Cloud. Its Zhenwu M890 processor is used through cloud services by more than 650 external customers across over 20 industries, while QwenWork, DingTalk and Qwen Shopping Assistant connect models with enterprise and commerce workflows. Instant retail and the 64 million-member 88VIP base add consumer scale alongside the cloud transition.
Alibaba Group (BABA) Q1 FY2027 Earnings Overview: Revenue Beat, 45% Cloud Growth and Profit Pressure
Alibaba delivered RMB 268.953 billion (USD $39.63 billion) in quarterly revenue versus roughly RMB 262.1 billion (USD $38.62 billion) expected, while adjusted EPS per ADS of RMB 8.52 (USD $1.26) missed the RMB 10.72 (USD $1.58) consensus. AI Cloud and Compute revenue rose 45% to RMB 48.437 billion (USD $7.14 billion), and cloud adjusted EBITA increased 133% to RMB 5.628 billion (USD $0.83 billion), while net income fell 75% to RMB 10.444 billion (USD $1.54 billion). The quarter strengthened the AI demand case, but RMB 67.7 billion (USD $9.98 billion) of capex and negative free cash flow of RMB 44.67 billion (USD $6.58 billion) kept the timing of investment returns central to the valuation debate.
Read More: Alibaba (BABA) Q1 2027 Earnings Overview: RMB48.44B AI Cloud Growth Drives a 1.26% Price Rally
|
Financial Metric |
Guidance / Consensus |
Reported / Actual |
Surprise |
|
Q1 FY2027 revenue |
RMB 262.1B (USD $38.62B) consensus |
RMB 268.953B (USD $39.63B) |
Beat. Approximately RMB 6.9B (USD $1.02B) above consensus; up 9% YoY. |
|
Non-GAAP diluted EPS per ADS |
RMB 10.72 (USD $1.58 per ADS) consensus |
RMB 8.52 (USD $1.26 per ADS) |
Miss. RMB 2.20 (USD $0.32 per ADS) below consensus as investment increased. |
|
Net income |
— |
RMB 10.444B (USD $1.54B) |
Declined. Down 75% YoY. |
|
Operating profit |
— |
RMB 15.161B (USD $2.23B) |
Declined. Down 57% YoY despite revenue growth. |
|
AI Cloud and Compute revenue |
— |
RMB 48.437B (USD $7.14B); +45% YoY |
Accelerated. Fastest cloud growth in 22 quarters. |
|
AI-related product revenue |
— |
RMB 12.376B (USD $1.82B) |
Accelerated. Triple-digit growth for 12 consecutive quarters. |
|
Cloud adjusted EBITA |
— |
RMB 5.628B (USD $0.83B); +133% YoY |
Expanded. Margin reached approximately 12%. |
|
China instant retail revenue |
— |
RMB 53.295B (USD $7.85B); +45% YoY |
Expanded. Scale increased as unit economics improved. |
|
Capital expenditure |
— |
RMB 67.7B (USD $9.98B) |
Increased. Up 75% YoY for AI infrastructure. |
|
Free cash flow |
— |
RMB 44.67B (USD $6.58B) outflow |
Weakened. Infrastructure spending pushed cash flow negative. |
|
Cash and liquid investments |
— |
US$69.9B |
Strong. Liquidity supports continued investment. |
- Revenue of RMB 268.953 billion (USD $39.63 billion) grew 9% and beat consensus: The result came in about RMB 6.9 billion (USD $1.02 billion) above the roughly RMB 262.1 billion (USD $38.62 billion) estimate. Faster cloud and instant-retail growth helped broaden expansion beyond core China commerce.
- Adjusted EPS per ADS of RMB 8.52 (USD $1.26) missed by RMB 2.20 (USD $0.32): Consensus was near RMB 10.72 (USD $1.58), while net income fell 75% to RMB 10.444 billion (USD $1.54 billion). The gap shows that heavier technology and consumer investment is still limiting per-share earnings growth.
- AI Cloud revenue reached RMB 48.437 billion (USD $7.14 billion), up 45%: AI-related product revenue also rose to RMB 12.376 billion (USD $1.82 billion) after a twelfth straight quarter of triple-digit growth, showing that Qwen and compute demand are becoming meaningful commercial workloads.
- Cloud adjusted EBITA rose 133% to RMB 5.628 billion (USD $0.83 billion): Segment margin reached about 12% even as infrastructure investment increased. That supports the operating-leverage case, although group operating profit still declined 57%.
- Capex of RMB 67.7 billion (USD $9.98 billion) drove negative free cash flow of RMB 44.67 billion (USD $6.58 billion): Spending rose 75% year over year, making cash conversion the quarter’s main tradeoff. Alibaba’s roughly USD $69.9 billion liquidity position supports the buildout, but prolonged negative free cash flow would weaken the value created by faster cloud growth.
Alibaba Group (BABA) Price Prediction 2026: Bull vs. Bear Scenarios
The central test is whether cloud growth above 40% and a roughly 12% cloud EBITA margin can outweigh weaker group profit, negative free cash flow and equity dilution. All prices below refer to the U.S.-listed BABA ADR in USD and are BingX Academy editorial scenarios rather than Wall Street targets.
The Bull Case: Strong AI Cloud Growth Pushes BABA Toward USD $230
The Bull Case assumes AI Cloud and Compute revenue stays near or above 40% growth, cloud adjusted EBITA continues rising faster than sales, and Qwen adoption expands across more enterprise workloads. Instant retail also remains strong while losses narrow, allowing cloud profitability and better commerce efficiency to rebuild group earnings.
A move toward USD $210 to $230 would require free cash flow to turn positive, cloud margin to rise above roughly 12%, and management to show clearer returns on RMB 67.7 billion (USD $9.98 billion) of quarterly capex. Lower dilution and stronger China consumption would provide further support.
The Base Case: Steady Cloud Growth Keeps BABA Between USD $150 and $180
The Base Case assumes cloud growth moderates into the 30% to 40% range, AI-related revenue remains a meaningful share of cloud sales, and commerce investment continues to pressure group margins. Alibaba’s roughly USD $69.9 billion liquidity position supports expansion, while free cash flow recovers only gradually.
Under this scenario, BABA could trade mainly between USD $150 and $180. Continued cloud EBITA growth and narrower instant-retail losses would support the range, while cloud growth below 30%, another large equity raise, or persistent negative free cash flow would weaken it.
The Bear Case: Heavy AI Spending and Dilution Pull BABA Toward USD $90
The Bear Case assumes AI infrastructure spending stays elevated without a matching improvement in cloud margins. Domestic commerce competition keeps customer-acquisition costs high, China consumption remains soft, and the HK$80 billion placement fails to generate returns quickly enough to offset dilution.
A move toward USD $90 to $110 would become more likely if cloud growth falls below 25%, operating profit keeps declining sharply, or free cash flow remains materially negative. Export controls or renewed ADR policy concerns could add further valuation pressure.
BABA Stock Price Forecasts for 2026 By Wall Street Analysts
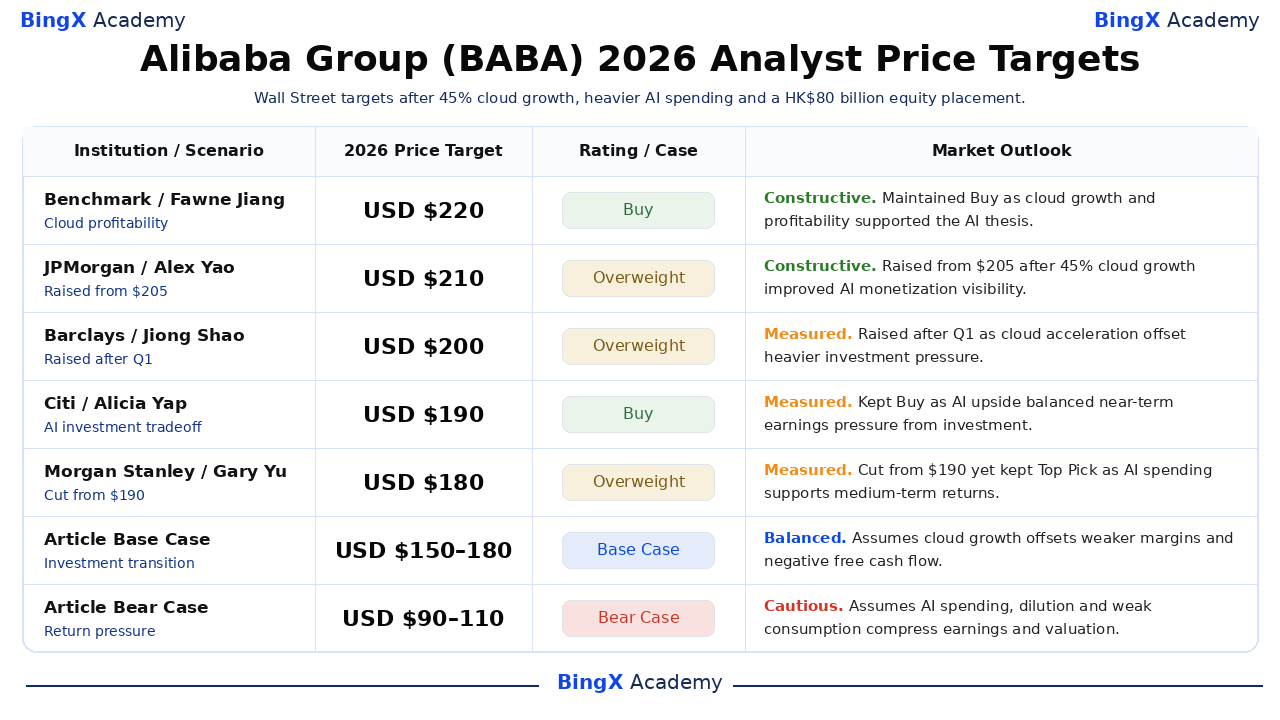
The six selected institutional actions range from USD $170 to $220 per ADR and preserve each firm's latest stated rating and target direction. The wider consensus sits near USD $187 to $196, showing substantial upside from the September 4 close alongside meaningful uncertainty over investment returns. The final two rows are BingX Academy editorial scenarios rather than Wall Street forecasts.
|
Institution / Scenario |
2026 Price Target |
Rating / Case |
Market Outlook |
|
Benchmark |
USD $220/ADR |
Buy |
Constructive. July 9: maintained Buy as cloud growth and profitability supported the long-term AI thesis. |
|
JPMorgan |
USD $210/ADR |
Overweight |
Constructive. August 21: raised from $205 after 45% cloud growth improved AI monetization visibility. |
|
Barclays |
USD $200/ADR |
Overweight |
Measured. August 21: raised after Q1 as cloud acceleration offset heavier investment pressure. |
|
Citi |
USD $190/ADR |
Buy |
Measured. August 20: kept Buy as AI upside balanced near-term earnings pressure from investment. |
|
Morgan Stanley |
USD $180/ADR |
Overweight |
Measured. July 26: cut from $190 yet kept Alibaba as a Top Pick for medium-term AI returns. |
|
HSBC |
USD $170/ADR |
Buy |
Cautious. July 9: cut from $176 as AI and commerce spending weighed on near-term earnings. |
|
Article Base Case |
USD $150–$180/ADR |
Base Case |
Balanced. Assumes cloud growth offsets weaker margins and negative free cash flow. |
|
Article Bear Case |
USD $90–$110/ADR |
Bear Case |
Cautious. Assumes AI spending, dilution and weak consumption compress earnings and valuation. |
How to Trade Alibaba Group (BABA) Stock on BingX
Trade Alibaba's AI-cloud growth, Qwen adoption, commerce efficiency and free-cash-flow outlook using BingX TradFi and BingX AI tools. Because BABA can react sharply to earnings, China policy, equity financing and U.S. technology restrictions, traders should define both the catalyst and risk limits before entering a position.
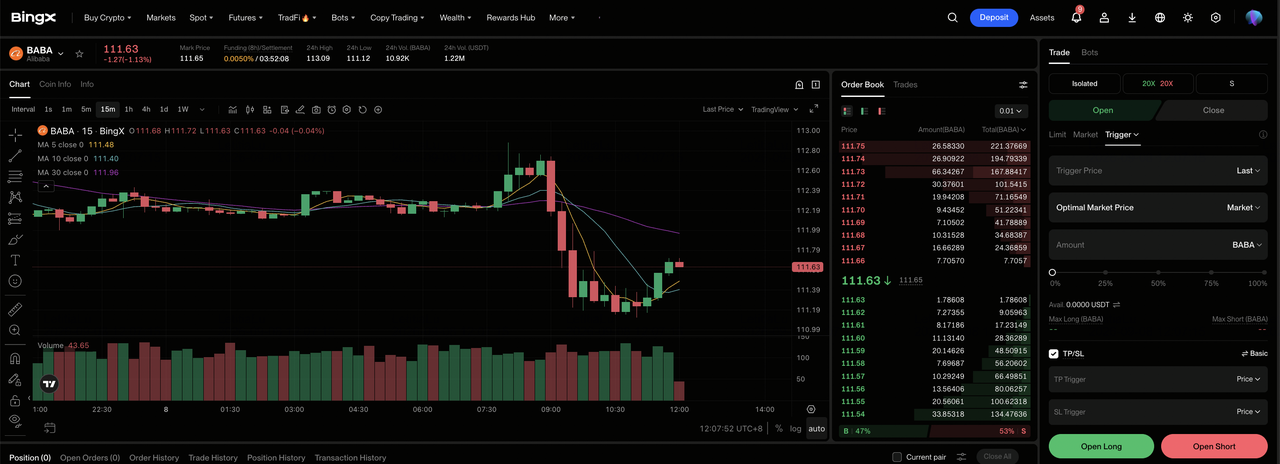
Step 1: Access BingX TradFi. Sign up and navigate to the specialized TradFi section on the BingX exchange dashboard.
Step 2: Select Alibaba Group (BABA). Search for and select the BABA-USDT perpetual futures contract.
Step 3: Choose your direction. Select Open Long if cloud growth remains above 40% and margins improve. Select Open Short if investment, dilution or weak commerce demand reduce per-share earnings.
Step 4: Select leverage and margin mode. Choose Isolated or Cross-Margin based on your risk tolerance. The 22.75% YTD decline shows why conservative leverage and clear position sizing are important.
Step 5: Execute strict risk protocols. Set Take-Profit and Stop-Loss (TP/SL) levels before or immediately after entering the trade. BABA can react quickly to cloud growth, commerce margins, capital spending, equity issuance and China policy.
Top 5 Risks to Watch for BABA Investors in 2026
Alibaba's faster cloud growth improves the long-term opportunity, although the ADR remains exposed to operating, financing and policy risks that can directly change per-share value.
- RMB 67.7 billion (USD $9.98 billion) of quarterly capex increased 75%: The spending contributed to a RMB 44.67 billion (USD $6.58 billion) free-cash-flow outflow. If cloud growth or margins slow before infrastructure utilization rises, lower cash conversion would reduce the value created for each ADR.
- Net income fell 75% to RMB 10.444 billion (USD $1.54 billion): Instant retail and AI investment expanded faster than near-term profit. Continued competition from JD.com, Meituan and PDD could require subsidies that suppress margins and delay the earnings recovery embedded in higher scenarios.
- The HK$80 billion placement issued 710 million shares: New equity expands funding capacity and increases the ordinary-share count by roughly 3.7%. If the capital does not produce sufficient AI returns, each ADR represents a smaller claim on earnings and cash flow.
- China macroeconomic and regulatory exposure remains material: Domestic commerce depends on consumer confidence, merchant activity and a stable platform-policy environment. Weaker spending or renewed regulatory intervention could reduce revenue growth and keep a larger risk discount on BABA.
- U.S. export controls and ADR structure add external risk: Restrictions on advanced chips could constrain AI capacity even with strong demand. Separately, geopolitical or audit-access disputes could increase the discount between Alibaba's operating progress and the valuation assigned to its U.S.-listed ADR.
Final Thoughts: Should You Invest in BABA in 2026?
Alibaba's Q1 FY2027 results provided strong evidence that AI demand is becoming commercial: revenue grew 9%, cloud revenue rose 45%, AI-related products maintained triple-digit growth and cloud adjusted EBITA increased 133%. The counterweight is equally clear. Adjusted EPS missed consensus, net income fell 75%, capital expenditure reached RMB 67.7 billion (USD $9.98 billion) and free cash flow turned materially negative.
The USD $150 to $180 Base Case assumes cloud growth and improving segment profitability offset heavy investment gradually. The USD $210 to $230 Bull Case requires positive cash flow and better commerce efficiency, while the USD $90 to $110 Bear Case reflects weak returns, dilution and policy pressure. Investors should monitor cloud growth, cloud EBITA margin, instant-retail losses and free cash flow before treating the ADR's valuation gap as durable upside.
Risk Reminder: These BABA ADR scenarios are conditional research estimates, not investment advice or guaranteed returns. Alibaba's ADR and BABA-USDT perpetual contracts can lose value, and leveraged positions may be liquidated. Review current market data, company filings and BingX terms independently before taking risk.
Related Reading
- Top 10 AI Infrastructure Stocks to Buy in 2026: Chip Manufacturing and Design Leaders
- Top AI Compute and GPU Stocks to Buy in 2026: The Shift to Inference and Custom Silicon
- Top AI Cloud Infrastructure Stocks to Buy in 2026 Amid Hyperscaler Capex and the Neocloud Boom
- What Is Ondo's Alibaba Tokenized Stock (BABAON) and How to Buy It?
- Amazon (AMZN) Price Prediction 2026: Can AWS and AI Growth Push AMZN Past $400?
- Walmart (WMT) Price Prediction 2026: Can E-Commerce and Advertising Push WMT Toward $155?
